Great Britain · Evidence desk · 18+
Bank Cut-Off Times: The Clock After Release
 Partner campaigns: United KingdomUpdated 18 November 2026
Advertisement · 18+. Bonus, rating and review figures come from the campaign; they are not independently verified reviews. Check eligibility, availability and current terms. Listing does not establish local licensing.
There is no single UK-wide payout time. A useful estimate starts by separating operator approval, payment-rail delivery and the receiving provider’s posting time.
Quick answer
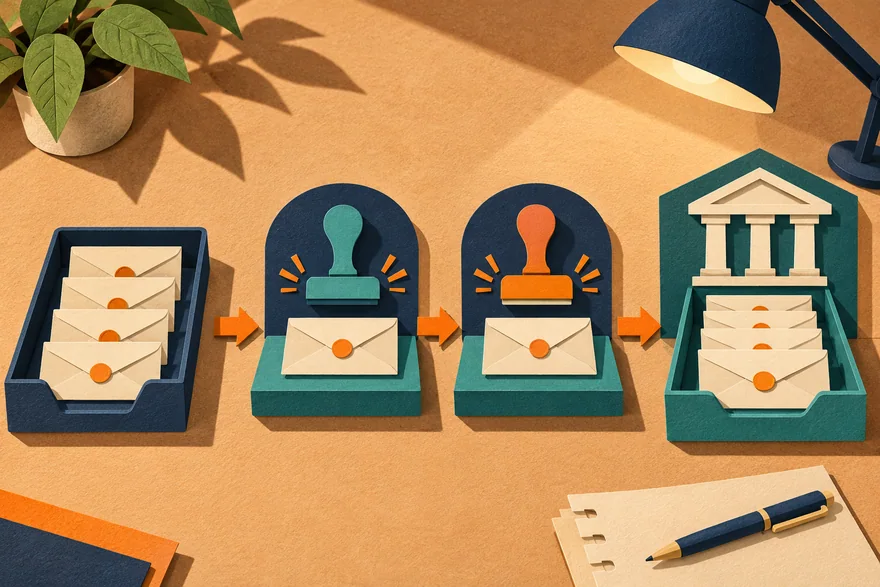
Once a payout is released it enters the banking layer, and the banking layer has its own rules: which scheme carries the payment, whether that scheme settles on working days, and what cut-off your receiving bank applies.
Domestic sterling payments in the UK are commonly carried by a fast payment service that operates outside normal banking hours, which is why some payouts arrive at night or at a weekend. Other payments use schemes that settle on working days only.
So after release, the two questions are which scheme and which bank. Neither is the operator’s to answer, and both need the release date and reference to investigate.
Schemes behave differently
Fast domestic payments are near-immediate and run continuously, subject to limits and the banks involved. Bulk schemes used for some payments settle over working days. International payments can pass through intermediary banks, each of which adds time and sometimes a fee.
Which scheme carries your payout is decided by the operator’s payment provider, not by you, and it is rarely stated. What you can establish is whether the payment was domestic and in sterling, which makes the fast route likely.
Where a payout crosses a currency boundary, expect the slower case and expect a deduction somewhere in the chain.
| Payment type | Typical speed once sent | Weekend behaviour |
|---|---|---|
| Fast domestic sterling | Minutes | Usually unaffected |
| Bulk domestic scheme | Working days | Pauses |
| Card credit | Issuer posting schedule | Varies by issuer |
| Wallet credit | Minutes to the wallet | Second leg separate |
| International transfer | Days | Pauses, intermediaries add time |
Cut-offs are per bank, not per country
Each bank sets its own cut-off times for sending and for applying incoming payments, and they differ. A payment released late in the day can be applied the next working day by one bank and immediately by another.
Your receiving bank’s behaviour is therefore part of the answer, and it is the part the operator cannot see. If a payment was released and has not arrived, the receiving bank is the right place to ask, with the release date and reference.
Bank holidays add to this and differ between the nations of the UK, so a long weekend can produce the longest version of the effect.
What your bank can actually do
Given a release date, an amount and a reference, a bank can look for an incoming payment and tell you whether it has arrived, is pending or is not visible. Without those three it has nothing to search and will refer you back to the sender.
That referral loop is the single most common reason these cases drag. Obtaining the release date and reference from the operator is therefore the step that unlocks everything else.
If the bank cannot see the payment and the operator insists it was released, the discrepancy is the complaint, and both sides’ statements with dates are the evidence.
- Ask the operator for the release date and the payment reference.
- Give both to the receiving bank when asking it to look.
- Expect per-bank cut-offs rather than one national rule.
- Bank holidays differ between the UK nations.
- A discrepancy between bank and operator is itself the complaint.
What this stage does not explain
It does not explain a payout that has not been released. If the operator has not sent the payment, no banking rule is relevant, and asking your bank wastes a day.
It also does not explain a deduction that the operator disclosed in its own terms. A fee stated in the withdrawal terms is a cost, not a banking event.
Keeping the two layers separate in correspondence is the whole skill here: the operator answers for review and release, the banking layer answers for delivery and posting.
A short routine after release
Record the release date and reference. Wait one working day for a domestic sterling payment, longer for anything crossing a currency or using a bulk scheme. Then ask the receiving bank with both facts.
If the bank does not see it, go back to the operator with the bank’s answer in writing. Two written statements that contradict each other is a strong, simple complaint.
- Obtain the release date and payment reference.
- Identify whether the payment is domestic sterling.
- Allow one working day for a fast domestic payment.
- Ask the receiving bank with date, amount and reference.
- Return to the operator with the bank’s written answer if needed.
FAQ
Why did my payout arrive at the weekend?
Because fast domestic sterling payments run outside banking hours. Once released, they do not wait for a working day.
Why did another payout take three working days?
Because it used a scheme that settles on working days, or it crossed a currency boundary with intermediary banks involved.
What does my bank need to trace a payment?
The release date, the amount and the payment reference. Without those it cannot search and will refer you back to the sender.
Are cut-off times the same everywhere?
No. Each bank sets its own, and UK bank holidays differ between nations, so arrival depends on your receiving bank’s calendar.
The operator says it was released and the bank cannot see it. What now?
Get both statements in writing with dates. A documented contradiction between the two is a clear complaint for the operator’s process.
Next pages
Sources
- Financial Conduct Authority: information for consumers, checked 18 November 2026.
- UK Gambling Commission: restrictions on withdrawing deposits and winnings, checked 18 November 2026.
- UK Gambling Commission: Licence Conditions and Codes of Practice, checked 18 November 2026.